A guide for England & Wales Questions about probate? raphael@myestatekit.co.uk
Family Matters
In focus · 4 min read · Co-created with a probate practitioner

She left them a will, a policy and a promise. Not one of them saved the house.

She had a will. She had a life policy. She had a promise. The one thing she didn't have was a plan — the sequence her family needed the morning after. This is what that cost them.

Three weeks before Mum died, she made us promise one thing: “Keep the house in the family.” Six months later, I sold it to a stranger.

My name's Carol. I'm 64 — two daughters, three grandchildren, a semi in Harrogate. I had a folder of my own too, a blue one, in the bureau at home, where I thought I'd planned for everything, for when the day came.

We promised. We meant it. I want to tell you how, six months later, I signed it away to a stranger — and why none of it was my mother's fault.

Mum died on a Tuesday morning, at 7:03. She was 89.

The next day I drove over to Dewsbury. The house was empty for the first time in forty years. Her tea was still on the kitchen table, half-drunk. On the bureau, her diary lay open at the Thursday — an appointment with the cardiologist she'd never keep. And in the garden, the cherry tree Dad planted in 1964 was just coming into blossom.

It was sitting down on the sofa — that sofa — that I remembered what she'd made Helen and me promise her, three weeks before: that the house would stay in the family.

Two days later the funeral deposit fell due — £4,850. I went into the bank with the invoice and the death certificate. I thought that, at least, would be simple: I knew the bank could pay the funeral director directly from Mum's account, before probate — they do it every day, you just bring them the invoice.

The woman behind the counter nodded.

“That's right, madam. We can settle the funeral director's invoice straight from your mother's account.”

She typed. Her face went still.

“But her current account only has £820 in it.”

It took me a few seconds to understand. “And — her savings? She had an ISA.”

“Empty. For the last eighteen months.”

I thought at once of the life policy. Mum had mentioned it once, years before — “I've put a bit aside for the two of you.” Nothing more. I'd never seen it. I didn't know the company, or the amount.

“My mother had a life policy. Can I get at that?”

“If it's a life policy, that's not us — that's a different thing, the insurer deals with it. You'd need to find the paperwork, work out the provider, put a full claim together. One to three months. Without the policy in front of you, there's nothing anyone can do.”

She said it the way you'd say a thing was out of stock. I stood there at the counter.

“So in practice, you'll transfer £820 to the funeral director.” “In practice, yes. The remaining £4,030, you'll have to advance yourselves.”

I rang Helen that evening. Before I'd even finished the sentence, I heard her voice close.

“Carol, I can't. Jack's at university, there's the mortgage — I haven't got that kind of money. And anyway, you kept her papers. It was up to you to know.”

She hung up. I stood a long time with the phone in my hand.

That night, in my kitchen in Harrogate, I took out a notebook and wrote one figure at the top of the page: £4,030. I looked at it a long time. That £4,030 wasn't coming out of Mum's account. It was coming out of mine. And it was out of mine that, within six months, I'd also have to find the Inheritance Tax on the house. I didn't know how much yet. But I knew that every pound I spent in the meantime was a pound closer to not keeping the promise.

I paid the deposit the next morning. It wasn't a bill any more. It was the first piece of the house, leaving.

Over the next fortnight the recorded letters piled up. Her pension had kept paying for two months after she died; now they wanted £3,280 back, penalties and all — thirty days to repay. Helen didn't answer my messages. I crossed out a second figure in the notebook. I hadn't even seen the solicitor yet.

One Saturday in May I went back to the house. I needed to read something that gave me a bit of air. In the sideboard drawer, between two postcards from 1987, I finally found it — the policy Mum had mentioned ten years before. Aviva. £38,000.

I read it three times. I closed it. I cried for two minutes — out of relief. A company at last, a policy number, a figure. I could claim. It would cover almost all the tax. The house was safe.

I rang Aviva on the Monday, at 9:04. They keyed in the policy number. There was a silence. Then, calmly, just like the woman at the bank:

“I'm sorry, madam. She took this out in 1994 — but it was never written in trust. Almost nobody is told to. That means it forms part of your mother's estate.”

I asked what that meant, in plain terms.

“That you can't count on this money to pay the Inheritance Tax, madam. It goes back into the estate with everything else. Count eight months, at the very least, before anything can be released.”

I hung up. I stood in the kitchen with the policy in my hand. And that was the moment — not at the bank, not on the phone to Helen — that I understood, for the first time, that I was going to lose the house.

The solicitor saw me ten days later. He was gentle about it.

“There's Inheritance Tax to pay — around £47,800, due within six months. And here's the part families never see coming: you can't get the grant of probate that lets you sell the house until the tax is paid. But the money to pay it is locked in the estate until the grant comes through.”

I had to pay the tax before I could sell the house to pay the tax.

I tried everything. My own bank — where I'd been a customer for thirty-eight years — turned down a bridging loan in three days. A second turned me down in five. The reason was always the same: “Your situation's a little too unusual, madam.” And while I chased the money, the sixth month slipped past me. I filed four days late. £1,310, added on automatically. I paid it. I couldn't tell you now with what.

In early September a developer turned up at the solicitor's office. He knew everything — the freeze, the refused loans, the deadline. He even knew Helen wasn't speaking to me. He offered 20% below the market price. Take it, he said, or wait another three months and let the interest finish the job. I looked at him, at his striped tie. I looked at Helen, on a chair beside me, staring at her hands. And I saw myself driving back to Harrogate that evening to tell my two daughters that their grandmother's house had been sold to pay the taxman. I didn't have a choice left.

The signing took fifteen minutes. Thirty-four pages. Helen never once looked up. I signed with the developer's pen — mine was at home, left behind in the rush.

That day, I didn't feel as though I'd sold a house. I felt as though I hadn't kept my promise.

The house was pulled down in February. Sophie drove past by chance one weekend and sent me a photo. You couldn't even see where the cherry tree had been.


£14,620, it cost my family in the end — between the pension clawback, the taxman, the inflated fees, the higher-rate loan and the 20% knocked off the price. And a sister who didn't pick up the phone for fourteen months.

But the part that hurt most wasn't the money, and it wasn't even Helen's silence. It was knowing, every time I thought of her, that Mum had not been careless. She'd done everything she believed she was meant to do. The will. The policy she took out in 1994. The words on the sofa.

She was simply missing one thing: a system. A sequence. A way through.

Three weeks later, a friend put me in touch with Robert Hartley, a retired probate practitioner. He'd spent three years, with two colleagues, building the very thing my mother never had. He called it the 5-28-6 System.
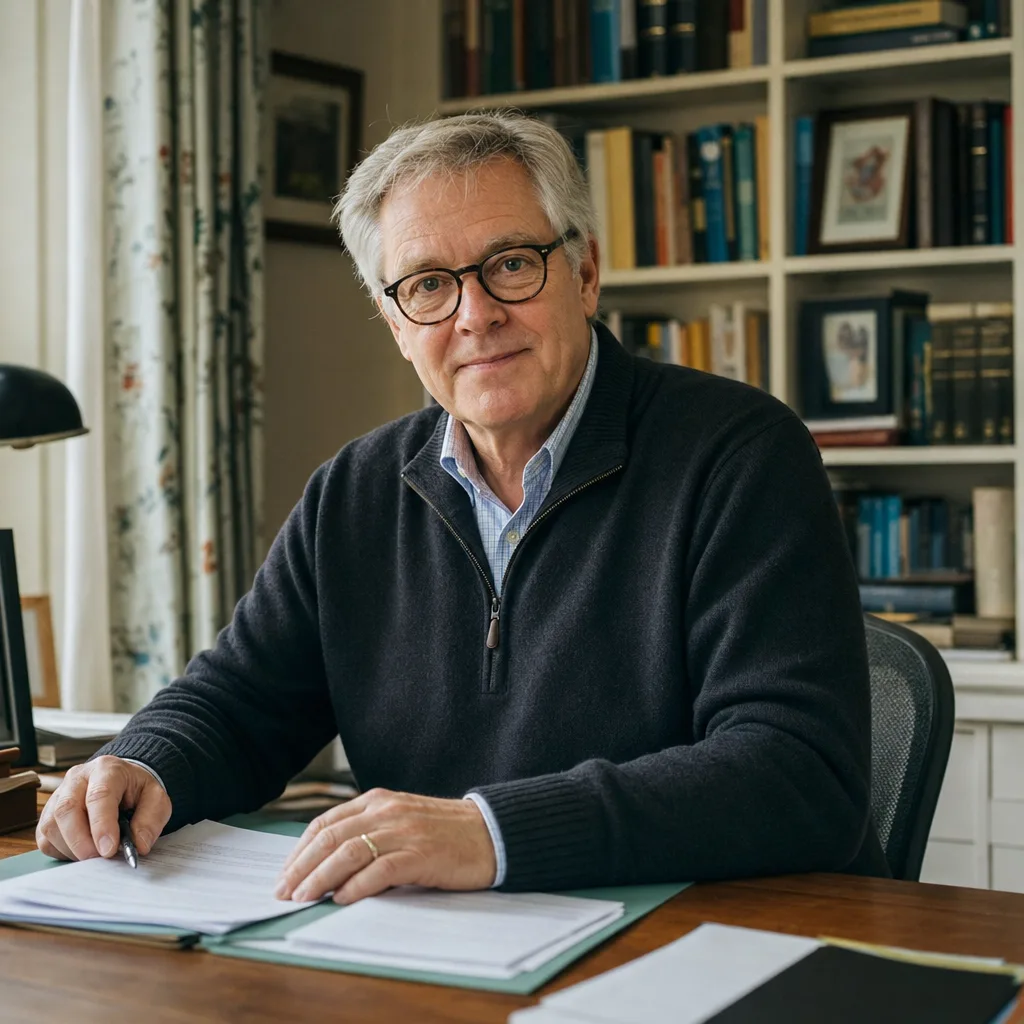
Robert Hartley, retired probate practitioner
Probate specialist (retired) · England & Wales
Robert Hartley
“In thirty years of probate work, two kinds of family came through my door. The ones who arrived with a folder — a real one, ordered, filled in — and left ninety minutes later with the estate mapped out. And the ones who arrived empty-handed, to whom I had to explain it could stretch over eight to eighteen months — recorded letters, fees, sometimes mediation, sometimes a house sold under pressure to meet a deadline. Both kinds loved their mother just the same. The difference came down to one thing: one had prepared, the other had said ‘we'll sort it later’.”
Over thirty years in probate & estate administration · Co-author of the 5-28-6 System

How it works

The plan, in four quiet steps.

1Download. It arrives by email within two minutes. One folder, three sections.
2Print. Any home printer will do.
3Fill it in. One afternoon, on your own or with your husband. Guided, no legal jargon.
4File it. In a drawer of your choosing. Tell one person you trust where it is. Done.
The Family Handover Kit
Leave them a plan — not a paper chase.
One-off payment · from £29 · instant access by email
Leave them a plan — from £29 →
✓ Instant email access✓ 30-day guarantee✓ Co-created with a probate practitioner
· · ·
The mechanism

Why 5, 28 and 6 — the three windows where it's won or lost.

What Robert Hartley learned in thirty years of probate: an estate in England isn't “managed” — it's triggered, at three moments where an unprepared family loses thousands of pounds and months of delay. Three moments. Three simple actions. Miss them, and each one costs.

5 days. A death must be registered within five days — and the will found, 10–15 certificates ordered, the funeral arranged. The bank pays the funeral director directly; everything else is frozen until probate. Without the right request in the folder, your family fronts the £4,000 and waits months for it back.

28 days. Tell Us Once tells the government — not the bank, the pensions, the insurers. Ring them in the wrong order and a private pension clawback lands: often thousands of pounds, thirty days to repay. Any account no one knew about is simply lost.

6 months. Inheritance Tax is due by the end of the sixth month, interest from the day after. The catch: the grant of probate that lets you sell the house isn't issued until the tax is paid — yet the money to pay it is locked until the grant. That's how a family sells the house under pressure, below value, to beat the clock.

Three windows. Three actions, prepared while you're well. One folder in a drawer.

The Family Handover Kit
The three windows, prepared in one afternoon.
One-off payment · from £29
Leave them a plan — from £29 →
✓ Instant email access✓ 30-day guarantee
· · ·
What's inside

Thirteen documents, in three windows.

5dWindow 1 — Register
  • The “Start Here” sheet — where the will is, who the executor is, who to call first.
  • Funeral wishes & the funeral-payment guide — the exact request that gets the bank to pay the director directly.
  • Death registration & certificates guide — the 5-day rule and why to order 10–15 copies.
28dWindow 2 — Notify
  • The complete account & asset register — every bank, ISA, Premium Bond, pension, policy and provider on one page.
  • The Tell Us Once + private notification map — who it covers, who it doesn't, and the order to contact the rest.
  • 12 ready-to-send notification letters — one per organisation, in the right format.
  • Bereavement support to claim — the payments many families never claim, with deadlines.
6mWindow 3 — Settle
  • The probate document checklist — every paper the application needs, in the order to gather them.
  • The estate value worksheet — assets and debts laid out the way the accounts need them.
  • The 6-month deadline calendar — every milestone on one page, with 14 days' warning.
  • The executor's mistakes to avoid + the professional handover sheet for a clear, costed first meeting.

I put my pen down. And I thought about you.

So far I've told you my story — a woman who buried her mother, broke a promise she never meant to break, and realised she'd leave her own daughters exactly the same corner if she did nothing.

But I don't know you. You might be in your kitchen, a coffee going cold beside you. You might be 58, or 69, or 72. You might have a house you'd give anything to keep in the family — and a quiet promise of your own, spoken or not.

And you might have a drawer somewhere, or a folder, or an “important papers” envelope. And you know — quietly, even if you never say it — that if you went this Sunday, your children would open that drawer, sit on the floor, and ask the question Helen and I never managed to answer in time:

“Where do we even start?”

You don't make this folder for yourself. You make it so that, the day it comes, they don't lose the house — or each other — to a gap you could have closed in one afternoon.

There are two kinds of mothers.

After I buried mine, I understood something. There are two kinds of mothers, and they love their children exactly the same.

The first leaves her children a corner. Not out of unkindness — out of “I'll do it next year”, out of that very British reluctance to talk about it at all. Not fear of dying. Fear of deciding.

The second leaves her children a map. Not money — order. The proof that she thought of them right to the end. An envelope, a folder, a written voice that says: “My darlings, I've prepared the way. The house, the accounts, the order to do it in — it's all here. Follow it.”

My mother didn't get the chance to be the second kind. Perhaps she meant to. I'll never know.

But me — I want to be the second kind.

I want my daughters to open the envelope, recognise my handwriting, read the first line, and know. Because preparing your estate isn't preparing your death. It's preparing their six hardest months — and making sure the house you promised them is still theirs at the end of it.

She had a will. She had a policy. She had a promise.
What she didn't have was a plan.

While you're here

The things only you can prepare.

  • The list that gets the bank to pay the funeral director directly — so no one is left £4,000 out of pocket.
  • Why Tell Us Once leaves the bank, pensions and insurers untouched — and the one list that closes the gap.
  • Where to note whether a life policy is written in trust — weeks versus months for your family.
  • The single page of every account, pension, ISA and Premium Bond — so nothing is left unclaimed.
  • The 6-month deadline on a calendar with 14 days' warning — so the date is never the surprise it was for us.
  • What to write for an unmarried partner, who can otherwise be left with nothing under intestacy.
The Family Handover Kit
Three packs · choose the level of protection that fits.
Essential £29 · Settled Family £47 · Complete Peace of Mind £76
Choose your kit — from £29 →
✓ Co-created with a probate practitioner✓ 30-day guarantee✓ Free updates
The cost of the gap

From £29, once.

A will costs £90 or more — and still leaves your family hunting for everything it doesn't mention. The Family Handover Kit is what makes all of it findable, in the order they'll need it. In my mother's case, the penalties, the fees and the forced-sale discount came to £14,620 — and we still lost the house. The plan that would have spared her family that is from £29, once — with free updates when the guidance changes.

Is the kit for you?

Yes, if…

  • You're 55–80 and you want your family to be alright on the day.
  • You own a home you'd want kept in the family.
  • You have two children or more, and no wish for them to fall out.
  • You'd rather spend one afternoon than leave them a paper chase.

No, if…

  • Your family already has one ordered register of every account they can find.
  • You have ready-to-send letters and a probate checklist prepared.
  • You're happy for them to wait months for access to money.
  • You have no one to protect after you've gone.

What people who've done it say

★★★★★
“I'd made a will years ago and thought that was the job done. Filling the folder in one rainy afternoon, I saw how much my daughters would have had to guess. It's in the bureau now, and they know it's there.”
Pauline R., 67
York
★★★★★
“When my husband died I spent four months chasing banks and pensions. I never wanted my children to go through that. The notification list alone would have saved me weeks.”
Janet H., 71
Shrewsbury
★★★★★
“We filled one in each — that was the part we'd never thought of. Two folders, same drawer. Neither of us is left starting from scratch.”
David & Sue P., 64
Norwich

Sources

  • GOV.UK — Register a death; Tell Us Once; Applying for probate; Pay your Inheritance Tax bill (figures as of 2026)
  • Exizent Bereavement Index — 87% found death admin stressful; 33% of executors had no prior knowledge of probate
  • STEP — survey reporting estate sales delayed or lost to probate hold-ups

At this point, you have two choices.

Carry on as before

Close this page. Tell yourself “I'll sort it later” — as I did, for three months. And let your children sit on the floor in front of a drawer, the clock already running, and ask: “where do we even start?”

One afternoon, this Sunday

Download the kit. Print it. Fill it in over a few hours. File it, and tell one person you trust. And get your Sunday back — knowing the house, and the family, are protected.

Questions people ask first.

I've already made a will. Why do I need this?
A will settles who inherits — which begins after probate. This covers the weeks before: when accounts are frozen, Tell Us Once doesn't reach the bank, and the family is hunting for documents. The two work together.
Will this stop the house being sold?
It can't promise that — every estate is different. What it removes is the panic: your family sees the deadline coming, knows where every account is, and gathers the right papers in order — so any decision about the house is made calmly and in time, not cornered to beat a clock.
I'm in good health. Isn't this premature?
It's exactly the right time. The kit takes one quiet afternoon now. Done in a rush at 75, the same job takes weeks and costs far more in fees.
Can't I find this free online?
Raw information, yes — Age UK and others publish good checklists. But a checklist is a list of tasks. It doesn't hold your NS&I holder number, your pension references, or which policy is written in trust. This is your information, gathered in the order they'll need it.
What if it's not for me?
You have 30 days to look it over at home. If it doesn't help you prepare, one email and we refund you. No questions, no paperwork.
Last step
Leave them the plan she never had.
One-off payment · from £29 · 30-day money-back guarantee
Get the Family Handover Kit — from £29 →
✓ Instant email access✓ 30-day guarantee

P.S. If you've read this far, a quiet voice said “what if it were me tomorrow?” That voice is right. The people who prepare aren't the ones afraid of dying — they're the ones who love their family too much to leave them this.

P.P.S. The house we lost wasn't taken by the taxman, or the bank, or the developer. It was taken by the gap — the days we spent guessing instead of acting. One afternoon today closes it. For you. For them.

The Family Handover Kit · A set of printable documents to help your family find key information and know where to begin after a death in England & Wales. Not a will, not legal or tax advice, and not a replacement for a solicitor. It does not avoid or speed up probate and cannot guarantee a property is kept or sold. A practical organiser. Figures are informational and drawn from GOV.UK and HMRC (as of 2026); confirm your own situation with a professional. 30-day money-back guarantee. Legal · Privacy · Terms · Refunds
© 2026 My Estate Kit · All rights reserved.